Someone has told you an irrevocable trust is the answer, maybe for Medicaid planning, maybe for protecting assets from a lawsuit, and it sounds right. Before you commit, whether this is your own decision or your parent's and you're the one doing the research, you want to know what nobody's telling you about the dangers of an irrevocable trust.
Here's the honest frame: an irrevocable trust is a powerful tool, and it's also a permanent decision. It isn't right for everyone. This is the downside, given to you straight, so you can decide with your eyes open.
What Makes an Irrevocable Trust Different
Once assets go into an irrevocable trust, you generally cannot take them back or change the terms. That permanence isn't a flaw in the design. It's the whole mechanism. The protection exists precisely because you, the grantor (the person who set up the trust and put the assets in), no longer control them.
We won't rebuild the full picture of how an irrevocable trust works here. What matters for this conversation is what that loss of control actually costs you.
The Real Dangers of an Irrevocable Trust
These are the trade-offs worth understanding before you sign anything.
You Give Up Control, Permanently
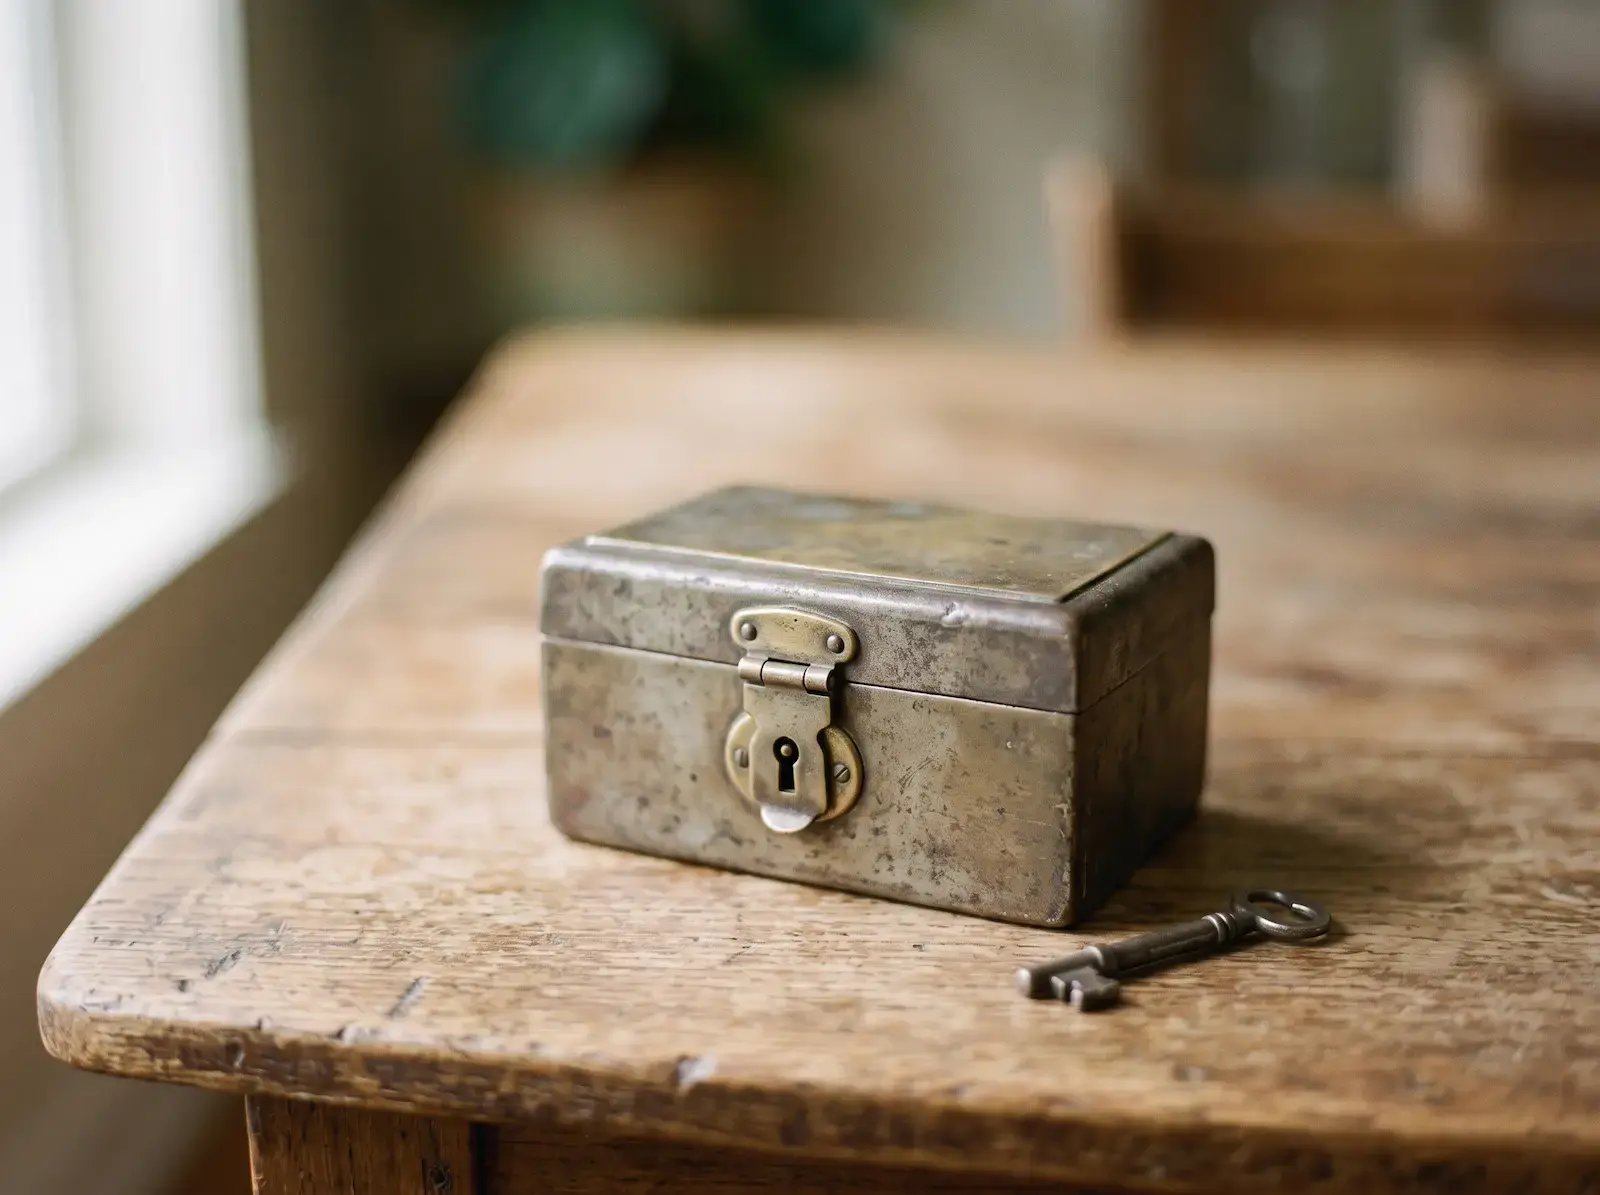
Once the trust is funded, you're no longer the owner of those assets. A trustee is. Think of it as putting your valuables in a lockbox and handing someone else the only key. You can't sell them, borrow against them, or reclaim them because you changed your mind. We say that plainly because softening it helps nobody: for most people, this is the one that actually stings.
Your Circumstances Can Change and the Trust Cannot
A divorce, a falling out with a beneficiary, a health crisis, a sudden need for cash. Life keeps moving, and the trust doesn't adapt to any of it. Picture someone who transferred the family home into an irrevocable trust, then years later needed to sell it to fund their own care. That option is gone once the transfer is made.
The Five-Year Clock Starts When You Fund It, Not When You Sign
Signing the trust document doesn't start the clock. Funding it does. Connecticut's Medicaid look-back means assets transferred within five years of applying for benefits can trigger a penalty period, and people who set up the trust but delay actually moving assets into it lose the time they thought they'd already banked. The Medicaid asset protection trust page covers the look-back rules in full.
Choosing the Wrong Trustee Is Hard to Undo
The trustee controls the assets, and you can't simply replace them if the relationship sours. A family member named as trustee can create real tension at family gatherings for years. A professional trustee avoids that tension but charges ongoing fees. This decision deserves more thought than most people give it.
It Costs More to Set Up and Maintain
An irrevocable trust costs more upfront than a revocable trust or a simple will, and the extra expense doesn't stop at signing. It typically requires its own tax filings and ongoing administrative attention for as long as it holds assets.
It Does Not Protect Against Everything
An irrevocable trust can't undo a claim that already exists. If a lawsuit is already filed, or a creditor already has a known claim against you, transferring assets afterward can be unwound in court as a fraudulent transfer. And a trust that isn't properly funded, meaning assets were never actually retitled into it, protects nothing at all.
Can an Irrevocable Trust Be Changed or Amended?
Sometimes, but not easily, and not unilaterally. A handful of routes exist: getting consent from every beneficiary, petitioning a court, decanting (moving the assets into a newly drafted trust), or relying on a trust protector provision, a clause written in at the start that lets a named person make limited changes later.
The practical takeaway is that building flexibility in at drafting is far easier than fixing rigidity later. That's an argument for careful, deliberate drafting, not an argument for avoiding an irrevocable trust altogether.
Who Should Think Twice About an Irrevocable Trust
Think twice if you might need those assets for your own living expenses down the road. Think twice if your situation is still in flux: a recent marriage, young children, finances that haven't settled yet. Think twice if your estate falls well under Connecticut and federal estate tax thresholds and you have no long-term care concern driving the decision. And think twice, always, if anyone is rushing you into signing.
Why Would Someone Want an Irrevocable Trust?
None of this means an irrevocable trust is wrong for you. People who choose one usually have a specific, real reason. Some are protecting the family home from long-term care costs, with enough runway to clear the five-year Medicaid look-back before they'd need it. Some are providing for a loved one with a disability without risking that person's needs-based benefits, which is where a special needs trust comes in.
Others have estates large enough to face Connecticut's estate tax, or work as professionals or business owners carrying real liability exposure, which is where an asset protection attorney can help sort out what's actually at risk.
The right answer depends on your full picture, not on any one of these reasons in isolation. That's what a consultation is for.
Frequently Asked Questions About Irrevocable Trusts
Get Advice Before You Commit
You're weighing a permanent decision, and maybe not even for yourself. Maybe it's for a parent, and you're the one doing the research because they can't, or shouldn't have to.
Before anything is signed, we'll walk through whether an irrevocable trust actually fits your full picture, or whether something else serves you better. Schedule a free strategy session whenever you're ready, and there's no cost for that first conversation.